Why IRAs can be a Challenge in Retirement and What to do About It
POSTED ON
Individual Retirement Accounts (IRAs) often take center stage as a go-to savings vehicle when planning for retirement. While IRAs offer numerous benefits, including tax advantages and the potential for long-term growth, they can also pose some unexpected challenges that could derail your retirement plan as you age.
Let’s dive into the reasons why IRAs can become problematic in retirement and explore strategic approaches to mitigate these issues. Whether you're nearing retirement or just beginning your financial planning journey, understanding the potential pitfalls of IRAs and how to navigate them is crucial for securing a comfortable and stress-free retirement.
5 Challenges IRAs Pose in Retirement
Challenge #1: Current tax rates are historically low
By holding a large percentage of your wealth in a pre-tax IRA, you are subjecting yourself to forces outside of your control. With both the top and bottom marginal tax rates at relatively low levels compared to history and with government spending continuing to climb higher, you may find yourself putting less in your pocket from your pre-tax IRAs than you thought when you were contributing. Couple those facts with the Tax Cuts and Jobs Act sunsetting in 2025, which will increase tax rates for many Americans. To put it simply, the tax deduction may feel good today, but your bill will come due at some point and you may pay more in the future than if you had decided to pay the tax today.
Challenge #2: Policy risk has increased
The wealth gap is growing, and for many, the solution is to increase taxes on top earners. As the cohort of people voicing their concern grows, top earners, and by default, distributions from pre-tax IRAs, become a larger target for policymakers.
Challenge #3: Medicare IRMAA surcharges
The Income-Related Monthly Adjustment Amount (IRMAA) is a cost imposed by Medicare on high income beneficiaries. In the government’s eyes, you must pay more for your healthcare if you have more resources. The income used to determine IRMAA is your AGI + municipal bond interest from two years ago. The untaxed portion of Social Security benefits is not included. Your income from 2020 will determine your IRMAA for 2022. 2021 income will determine IRMAA for 2023 and so on.
Challenge #4: “Widow’s penalty”
As a surviving spouse moves out of the Married Filing Jointly tax filing and into the Single tax filing, tax rates are increased by about 10%. Total Medicare payments often stay the same or even increase in some cases even though only one person is covered instead of two. You can start to think through how having the bulk of your wealth in a pre-tax IRA limits your flexibility in navigating these changing circumstances.
Challenge #5: 10-year rule for inherited IRA’s
The number one goal of anyone saving or planning for retirement is to take care of their needs first, but what happens if you can’t spend all your money before you die? If a non-spouse beneficiary inherits a pre-tax IRA, it could spell trouble for their tax situation. With the SECURE Act, non-spouse beneficiaries are now required to deplete (and pay income tax) on the entire IRA balance over 10 years. Often, this beneficiary is in the highest earning years of their career as well. The unintended consequence may be your beneficiary pocketing $0.60 for every dollar in your IRA.
Strategies to Mitigate IRA Challenges in Retirement
So, you’ve spent most of your working years contributing to your IRA to find out it may cause issues for you in retirement. The good news is by planning early and revisiting your plan often, there are strategies you can use to combat these issues.
Strategy #1: Review employer benefit plans (specifically, consider Roth 401k’s)
Most people contribute a percentage of their income into their 401k, usually enough to max out the match from their employer, and call it a day. It may be worth it to think through the contribution a little further, and maybe even consult a financial advisor to do some math for you. For many, taking advantage of the Roth 401k option if offered by their employer will provide a greater benefit in the long run, even after accounting for increased income taxes paid during your working years.
This rings especially true if you expect to be in a higher tax bracket in retirement or are accumulating wealth quickly. There may also be other nuggets to take advantage of in your employer benefits that allow you to accumulate wealth outside of the pre-tax IRA/401k vehicle, such as an employee stock purchase plan (ESPP) and deferred compensation options.
Strategy #2: Tax diversification
Storing wealth in different “tax buckets” will allow for greater control in distribution scenarios. By having money in pre-tax, taxable and tax-free accounts, you can build a strategy to put the desired amount of money in your pocket while staying in a lower tax bracket and avoiding extra costs, such as the IRMAA.
Strategy #3: Backdoor Roth conversions
To keep it simple, people who make a lot of money are phased out of contributing to Roth IRAs. By contributing to a non-deductible traditional IRA and then converting those funds into a Roth IRA, you can bypass (or backdoor) those rules and accumulate wealth in a bucket that will never be taxed again. For those under 50, you are limited to $6500 per year per person. If you’re 50 or older, that number increases to $7500.
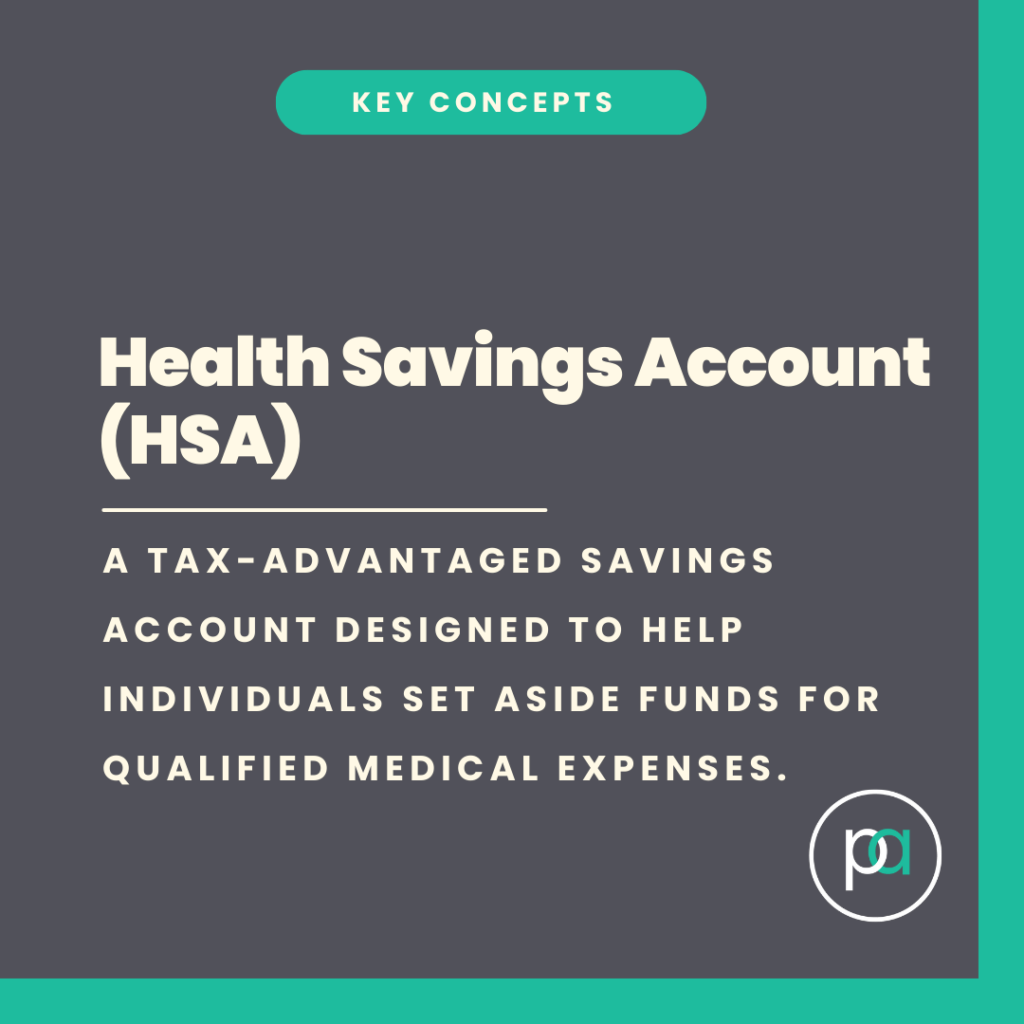
Strategy #4: Health Savings Accounts
This is the unicorn of the tax world. Contributions are deductible in the year contributed, can be invested and grow tax deferred, and can be withdrawn tax-free if used for qualified medical expenses, which are all but guaranteed to pop up during your lifetime. In 2023, you can contribute up to $7,750 if you’re covering a family. If you’re 55 or older, you can add an additional $1,000 catch-up contribution. When you hit retirement, you can use your HSA funds to pay for Medicare Part B, Part D and Medicare Advantage plan premiums, deductibles, co-pays and coinsurance. Alongside those expenses, use your HSA to pay for ibuprofen, allergy medicine, dental cleanings, glasses/contacts, and many other everyday items.
Strategy #5: Searching for tax alpha in non-qualified accounts
Tax alpha is the potential value created by effective tax management of investments. This is a year-round strategy being employed by everyone from savvy individual investors managing their own money to the big asset managers for an added cost. The strategies entail tax-loss harvesting, efficient tax lot trading and others. Ultimately, the goal is to defer taxes which allows for greater compounding. The same rate of return on a larger amount (compared to a smaller amount being consistently hit with more taxes) will produce better after-tax returns.
Strategy #6: Understand asset location
There are three types of ways to invest money from a tax standpoint: pre-tax and tax deferred, post tax and tax advantaged, and post-tax and taxable as you go. So, which one should house what type of investments? Other variables aside, you may want to consider placing slower growth and income yielding investments in your pre-tax and tax deferred bucket, such as a traditional IRA or pre-tax 401k. You will want your aggressive, high growth investments in your Roth IRA or Roth 401k. Ideally, buy and hold investments will go into taxable accounts.
Strategy #7: Roth conversions
Partial or full Roth conversions are an effective strategy for maximizing lifetime wealth. This strategy will convert traditional IRA money to Roth IRA money through a realization of income in the year that the conversion takes place. This may especially make sense for someone who will be in a low tax bracket in one year compared to other years.
Once you convert the IRA dollars, and if you’re under 59 ½ years of age, you will be penalized for withdrawals. Beyond those 5 years, you will have full access to the deposited amount. If you’re above age 59 ½, you have full access to those funds immediately, but the hope is that you will leave a portion in the Roth IRA for tax-free growth and distribution in the future.
There are no upper limits as to how much you are allowed to convert at one time, but the entire amount will be added to your gross income for the year. It is important to consult a tax advisor to discuss how to optimize the timing of conversions and amount to convert.
Strategy #8: Have a distribution strategy
Understanding tax brackets, lifestyle, expense needs, and the longevity of your portfolio assets will all play a crucial role in formulating a distribution strategy during retirement. Often, taking money from pre-tax or tax-deferred accounts early in retirement will increase control later and take advantage of lower tax brackets in those years. By reducing your RMD amount later in life, you will be able to maintain control over your taxable income.
Strategy #9: Qualified charitable distributions
Are you charitably inclined now or plan on leaving assets to charity at death? Qualified charitable distributions (QCD) allow individuals who are taking required minimum distributions to donate up to $100,000 to one or more charities directly from a taxable or regular IRA. As a result, donors may avoid being pushed into higher income tax brackets and prevent phaseouts of other tax deductions during RMD years. In this relationship, the donor may not maintain any advisory capacity over the funds once established and funds will be immediately available to the charity or charities of the donor’s choice.
There is also a “give later” option where those funds can be used to purchase life insurance with the donor as the insured. The same tax benefits apply today to the donor, and the charity will receive the death benefit upon passing.
Strategy #10: Estate planning, trusts and legacy planning
Let’s all agree that if you’ve made it this far, you have a desire to maximize efficiency, protect your hard-earned assets and have a say in who benefits from the wealth you accumulate over a life time. Working with a team of professionals to put a plan in place to fulfill your desires will ensure your wealth will be more efficiently used and often, protected from outside influence or crises.
If you’re ready to discuss what strategies might work best for your circumstances, we can connect you to one of our vetted financial advisor partners to ensure you’re set up for success in retirement.